This list proves a fundamental point: Bitcoin's mathematical security is unbreakable, and no one managed to crack it. The real weakness lies within corporations and their mistakes.
The issue in 2026 was not #bitcoin itself, but everything surrounding it: e-commerce websites getting customer data stolen, delivery services suffering cyberattacks, fake letters sent to people's homes, and software programming bugs.
When you buy a hardware wallet, you often leave your name, home address, and email on the manufacturer's website. If hackers steal that database, they know exactly that you own Bitcoin and where you live, making you a target for scams and fake letters (phishing).
Furthermore, blindly trusting a single company to protect all your money is a mistake: if that company messes up its software, your savings are at risk. True protection requires buying devices anonymously and, if necessary, using different wallet brands so you don't put all your eggs in one basket.
❓ Which of these 10 incidents in 2026 worried you the most or made you change the way you store your Bitcoin? Let me know in the comments! 👇
#bitcoin #plebs #security #privacy #primal #wallet
View quoted note →
Scudo Finanziario
scudofinanziario@nostrcheck.me
npub1th6e...4pa8
🇮🇹 Analizzo i mercati finanziari e spiego come eventi geopolitici, trend energetici e rivoluzione IA influiscono sui tuoi risparmi. Focus su Bitcoin, Oro e Macroeconomia per proteggere il tuo potere d'acquisto. [Solo scopi divulgativi]
🇬🇧 I analyze financial markets and explain how geopolitics, energy trends, and the AI revolution impact your savings. Focusing on Bitcoin, Gold, and Macro to protect your purchasing power. [Educational only]
⚡ NIP-57 Zaps are welcome!
#plebchain #bitcoin #macro
The $1.7T #bitcoin Paradox: Why 99% of Supply Rejects Counterparty Risk
Data from recent institutional reports shows a striking contrast: less than 0.6% of the circulating Bitcoin supply (around 104,000 BTC) is actively deployed in yield-generating DeFi strategies. Even among tokenized or "wrapped" variants like WBTC or cbBTC, nearly 65% remains economically idle.
From a broader perspective, as of October 2026, Bitcoin's total market capitalization stands at $1.71 trillion, making up roughly 1.65% of the total global M2 money supply. In traditional fiat finance, leaving such a massive capital stack unproductive would be considered a major mistake due to constant currency debasement.
In Bitcoin, however, this "idle" 99% represents a highly conscious choice. The market values the absolute scarcity and cryptographic security of pure HODLing far more than the marginal yield offered by smart contracts or centralized custodians. For the sophisticated investor, avoiding counterparty risk is the ultimate yield.
#macroeconomics #bitcoin #defi #finance #yield #hodl #btc #riskmanagement
Interest Rates: The France 🇨🇵-🇮🇹 Italy Paradox
How global monetary tightening is reshaping Eurozone debt risks
The synchronized global tightening by the Fed, ECB, and Bank of Japan (BoJ) in September 2026 is exposing structural vulnerabilities within the Eurozone, creating a historic financial paradox. France’s 10-year government bond yield has climbed to 4.87%, officially outstripping Italy’s BTP at 4.61%.
While Italy holds a higher overall debt-to-GDP ratio, markets are now penalizing Paris more severely due to its chronic fiscal deficits and ongoing political gridlock. Investors unwinding the Yen Carry Trade are demanding a higher risk premium for French OATs, pushing its spread over the German Bund to 132 basis points, well above Italy’s 114.6 bps.
The Eurozone is not facing an imminent default wave, thanks to extended debt maturities and the ECB’s backstops like the TPI. However, this historic yield inversion proves that global rate pressures are sorting countries by political stability and fiscal execution rather than just raw debt volume.
❓ Given this historic yield inversion, do you think the French spread will continue to widen against Italy's until Paris passes a structural budget, or are we looking at a permanent re-pricing of core Eurozone risk?
#macroeconomics #finance #eurozone #monetarypolicy #fed #boj #ecb #centralbanks #sovereigndebt #interestrates #carrytrade #france #italy
The synchronized global tightening by the Fed, ECB, and Bank of Japan (BoJ) in September 2026 is exposing structural vulnerabilities within the Eurozone, creating a historic financial paradox. France’s 10-year government bond yield has climbed to 4.87%, officially outstripping Italy’s BTP at 4.61%.
While Italy holds a higher overall debt-to-GDP ratio, markets are now penalizing Paris more severely due to its chronic fiscal deficits and ongoing political gridlock. Investors unwinding the Yen Carry Trade are demanding a higher risk premium for French OATs, pushing its spread over the German Bund to 132 basis points, well above Italy’s 114.6 bps.
The Eurozone is not facing an imminent default wave, thanks to extended debt maturities and the ECB’s backstops like the TPI. However, this historic yield inversion proves that global rate pressures are sorting countries by political stability and fiscal execution rather than just raw debt volume.
❓ Given this historic yield inversion, do you think the French spread will continue to widen against Italy's until Paris passes a structural budget, or are we looking at a permanent re-pricing of core Eurozone risk?
#macroeconomics #finance #eurozone #monetarypolicy #fed #boj #ecb #centralbanks #sovereigndebt #interestrates #carrytrade #france #italy🇨🇵 FRANCIA vs ITALIA 🇮🇹
Il mercato valuta i titoli di Stato in base alla fiducia e alle prospettive future, non solo sulla base dello stock di debito passato:
• Il deterioramento della Francia:
La Francia soffre di un deficit pubblico cronico ampiamente sopra i parametri europei e di una forte paralisi politica che rende difficili le riforme strutturali e i tagli alla spesa. Ciò ha causato ripetuti declassamenti da parte delle agiezie di rating e un aumento del premio di rischio richiesto dagli investitori.
• La stabilità dell'Italia:
Pur avendo un rapporto debito/PIL storicamente molto più alto, l'Italia sta mostrando una crescita economica moderata ma stabile, un avanzo primario migliore e una stabilità politica governativa che rassicura i mercati. Inoltre, gran parte del debito italiano è ora sostenuto dal risparmio privato interno e dai programmi della BCE.
#francia #italia #debito #bce #deficit
IL SORPASSO SUI TASSI
Sul mercato secondario, il rendimento dei titoli di Stato francesi (OAT) a breve e medio termine ha superato quello dei BTP italiani di pari durata.
Questo significa che, per ogni miliardo di euro che la Francia deve chiedere in prestito oggi per rifinanziarsi, si trova a pagare tassi d'interesse superiori rispetto all'Italia.
#Francia #Italia #oat #btp #tassi
Interest Rates: How Japan and Fed Moves Influence European Debt
The impact of global monetary policy on Eurozone financial markets and the actual stability risks for sovereign bonds.
Global monetary dynamics have undergone a profound transformation, placing European financial markets in a complex position. On one hand, the Bank of Japan (BoJ) has progressively abandoned its era of negative interest rates, pushing its benchmark rate toward 1.25%. On the other hand, persistent inflationary pressures driven by geopolitical tensions and energy costs led both the Federal Reserve (Fed) and the European Central Bank (ECB) to reverse course and execute fresh interest rate hikes in September 2026.
To fully understand the global impact, we must look at a mechanism known as the Yen Carry Trade. For decades, international investors borrowed money in Japan at near-zero or negative interest rates to invest it in higher-yielding assets abroad, such as European or American government bonds. Now that Japan is raising rates, this strategy is no longer profitable. Investors are unwinding these positions and repatriating their capital to Tokyo, which triggers significant volatility and upward pressure on bond yields worldwide.
This coordinated global tightening directly impacts Eurozone sovereign debt, particularly in countries with higher debt-to-GDP ratios. With less international liquidity available and more competitive yields offered in the US and Japan, European governments must offer higher interest rates to issue and auction their bonds.
However, the financial sustainability of the Eurozone rests on structural factors that are profoundly different from past crises. The extended average maturity of public debt (which exceeds 7 years in many nations) ensures that rising market yields do not hit the entire stock of debt instantly. Instead, the higher costs apply very gradually only to new bond issuances. Furthermore, the ECB now possesses specific anti-fragmentation toolkits, such as the Transmission Protection Instrument (TPI), designed specifically to counter unjustified market speculation or abnormal yield spreads.
The Eurozone is undeniably facing a phase of increased pressure and rising borrowing costs, but it remains well-shielded within a framework of enhanced monitoring and robust structural safeguards.
#macroeconomics #finance #eurozone #monetarypolicy #fed #boj #ecb #centralbanks #sovereigndebt #interestrates #carrytrade
The impact of global monetary policy on Eurozone financial markets and the actual stability risks for sovereign bonds.
Global monetary dynamics have undergone a profound transformation, placing European financial markets in a complex position. On one hand, the Bank of Japan (BoJ) has progressively abandoned its era of negative interest rates, pushing its benchmark rate toward 1.25%. On the other hand, persistent inflationary pressures driven by geopolitical tensions and energy costs led both the Federal Reserve (Fed) and the European Central Bank (ECB) to reverse course and execute fresh interest rate hikes in September 2026.
To fully understand the global impact, we must look at a mechanism known as the Yen Carry Trade. For decades, international investors borrowed money in Japan at near-zero or negative interest rates to invest it in higher-yielding assets abroad, such as European or American government bonds. Now that Japan is raising rates, this strategy is no longer profitable. Investors are unwinding these positions and repatriating their capital to Tokyo, which triggers significant volatility and upward pressure on bond yields worldwide.
This coordinated global tightening directly impacts Eurozone sovereign debt, particularly in countries with higher debt-to-GDP ratios. With less international liquidity available and more competitive yields offered in the US and Japan, European governments must offer higher interest rates to issue and auction their bonds.
However, the financial sustainability of the Eurozone rests on structural factors that are profoundly different from past crises. The extended average maturity of public debt (which exceeds 7 years in many nations) ensures that rising market yields do not hit the entire stock of debt instantly. Instead, the higher costs apply very gradually only to new bond issuances. Furthermore, the ECB now possesses specific anti-fragmentation toolkits, such as the Transmission Protection Instrument (TPI), designed specifically to counter unjustified market speculation or abnormal yield spreads.
The Eurozone is undeniably facing a phase of increased pressure and rising borrowing costs, but it remains well-shielded within a framework of enhanced monitoring and robust structural safeguards.
#macroeconomics #finance #eurozone #monetarypolicy #fed #boj #ecb #centralbanks #sovereigndebt #interestrates #carrytradeLa Fed:
Le spinte inflazionistiche globali guidate dalle tensioni geopolitiche e dai costi energetici stanno spingendo la Federal Reserve (Fed) a mantenere i tassi elevati ed anche ad effettuare un ulteriore aumento.
Quando i tassi USA rimangono alti, i mercati emergenti e l'Eurozona subiscono una forte pressione competitiva sui propri titoli di debito, dovendo offrire rendimenti più alti per attrarre capitali.
#fed #tassi #debito #usa
Il Giappone e la fine del denaro a costo zero:
La Bank of Japan (BoJ) ha progressivamente abbandonato la sua politica di tassi negativi, spingendo il tasso di riferimento verso l'1,25% e oltre. Questo fenomeno ha innescato lo smantellamento del cosiddetto Yen Carry Trade. Per decenni, i grandi fondi internazionali hanno preso in prestito yen a tassi quasi nulli per investirli in asset ad alto rendimento all'estero (inclusi i titoli di Stato europei e americani). Con il rialzo dei tassi a Tokyo e il conseguente rafforzamento dello yen, gli investitori sono costretti a rimpatriare i capitali, vendendo i bond esteri e facendone salire i rendimenti (e quindi i costi di finanziamento per gli Stati).
#Giappone #Yen #bond #tassi
The aging state: France's pension system under structural pressure 🇫🇷
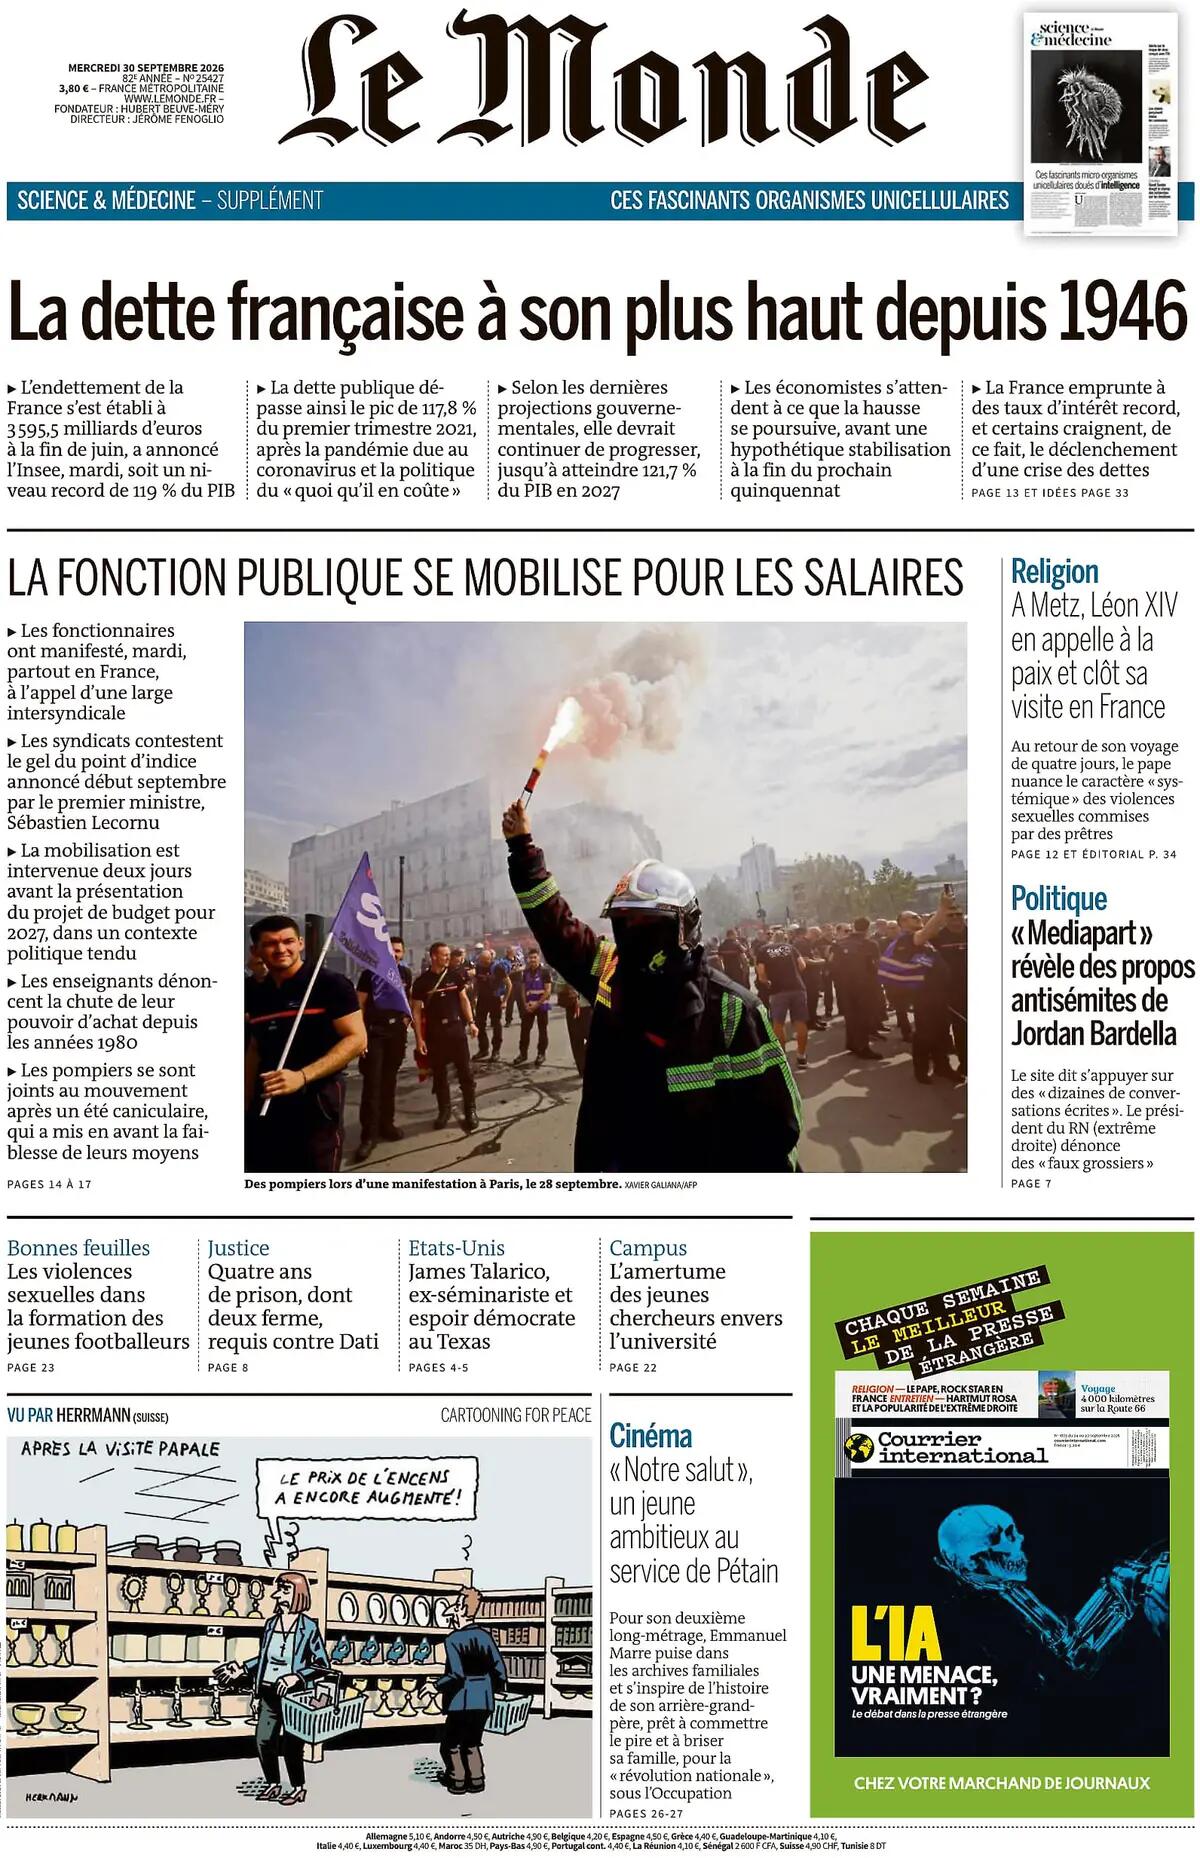
Pour mes lecteurs français : Voici la une d'hier (30 septembre) qui résume parfaitement la situation, suivie d'une analyse objective de la dette française et de la proposition d'Édouard Philippe de reporter l'âge de départ à 65 ans.👇
The presidential candidate and former Prime Minister, Édouard Philippe, has formally proposed raising France's legal retirement age to 65 years alongside expanding the mandatory contribution period to 45 years.
This announcement, which comes right after official data marked France's national debt at 119% of GDP, highlights the severe structural strain underlying European fiscal policy.
From a senior macroeconomic and geopolitical viewpoint, here is the clear breakdown of this development:
1️⃣ The Demographic Reality: Europe is aging. When the active workforce shrinks relative to the number of retirees, traditional pension systems—where current workers fund current retirees—face severe financial strain. Without structural changes, the math behind public welfare simply stops working, forcing public accounts into unsustainable losses.
2️⃣ The Austerity vs. Stability Paradox: As ongoing street protests show, implementing pension reforms triggers heavy social resistance. Governments are caught in a trap: failing to cut costs risks downgrades from credit rating agencies, but delaying retirement ages risks paralyzing the country through massive public unrest.
3️⃣ The Fiat Trap on a European Scale: This pension dilemma isn't unique to France—it is a shared vulnerability across the Eurozone. When real economic growth slows down, states lack the resources to keep their promises to citizens. To cover pension costs, governments have only two paths: increasing taxes on businesses and workers, or issuing new debt that is ultimately paid back by printing money and creating inflation. In both cases, the structural burden is shifted entirely onto future generations.
In conclusion:
This situation highlights a fundamental fracture within the modern economic architecture. On one side are the political promises of social welfare; on the other is the harsh reality of an aging population and empty public coffers. In the long run, the rigid constraints of traditional fiat money show their limits: when a state can no longer finance its social model through real economic growth, it is forced to either tax labor heavily or devalue its citizens' purchasing power through inflation. Understanding this dynamic is the first step to seeing why protecting your wealth is no longer an option, but a structural necessity.
[For educational purposes only — Not financial advice]
⚡ Zaps are welcome to support independent analysis!
#France #Pensions #LeParisien #Macroeconomics #Eurozone
The presidential candidate and former Prime Minister, Édouard Philippe, has formally proposed raising France's legal retirement age to 65 years alongside expanding the mandatory contribution period to 45 years.
This announcement, which comes right after official data marked France's national debt at 119% of GDP, highlights the severe structural strain underlying European fiscal policy.
From a senior macroeconomic and geopolitical viewpoint, here is the clear breakdown of this development:
1️⃣ The Demographic Reality: Europe is aging. When the active workforce shrinks relative to the number of retirees, traditional pension systems—where current workers fund current retirees—face severe financial strain. Without structural changes, the math behind public welfare simply stops working, forcing public accounts into unsustainable losses.
2️⃣ The Austerity vs. Stability Paradox: As ongoing street protests show, implementing pension reforms triggers heavy social resistance. Governments are caught in a trap: failing to cut costs risks downgrades from credit rating agencies, but delaying retirement ages risks paralyzing the country through massive public unrest.
3️⃣ The Fiat Trap on a European Scale: This pension dilemma isn't unique to France—it is a shared vulnerability across the Eurozone. When real economic growth slows down, states lack the resources to keep their promises to citizens. To cover pension costs, governments have only two paths: increasing taxes on businesses and workers, or issuing new debt that is ultimately paid back by printing money and creating inflation. In both cases, the structural burden is shifted entirely onto future generations.
In conclusion:
This situation highlights a fundamental fracture within the modern economic architecture. On one side are the political promises of social welfare; on the other is the harsh reality of an aging population and empty public coffers. In the long run, the rigid constraints of traditional fiat money show their limits: when a state can no longer finance its social model through real economic growth, it is forced to either tax labor heavily or devalue its citizens' purchasing power through inflation. Understanding this dynamic is the first step to seeing why protecting your wealth is no longer an option, but a structural necessity.
[For educational purposes only — Not financial advice]
⚡ Zaps are welcome to support independent analysis!
#France #Pensions #LeParisien #Macroeconomics #EurozoneFrance's debt hits 119% of GDP: A macroeconomic breakdown 🇫🇷
Pour mes lecteurs français :
Voici la une d'hier (30 septembre) qui résume parfaitement la situation, suivie d'une analyse objective de la dette française.👇
Recent data from France's statistical institute (INSEE) confirms that public debt reached 119% of GDP at the end of June. As the Eurozone's second-largest economy faces stagnant growth, the government is proposing €54 billion in spending cuts to bring the deficit down to 5% by 2027. This structural tension has already sparked over 170 public protests across the country.
From a senior macroeconomic perspective, here is what this structural data means for the Eurozone ecosystem:
1️⃣ The Sovereign Debt Dilemma: When public debt crosses structural thresholds during periods of economic stagnation, a government's fiscal space shrinks. This forces a delicate balancing act between austerity and political stability.
2️⃣ The Monetary Friction: Raising interest rates is designed to cool demand-driven inflation. However, it cannot solve supply-side shocks, such as the energy costs driven by current geopolitical tensions.
3️⃣ Fiat System Dynamics: In traditional fiat architectures, when governments struggle to cut spending due to social pressure, long-term debt pressures historically lead to monetary debasement (inflation) rather than technical defaults.
This situation highlights the ongoing friction between central bank tightening, fiscal deficits, and real economy constraints.
[For educational purposes only — Not financial advice]
⚡ Zaps are welcome to support independent analysis!
#France #Macroeconomics #ECB #INSEE #Finance #Economie #debt #dette
Recent data from France's statistical institute (INSEE) confirms that public debt reached 119% of GDP at the end of June. As the Eurozone's second-largest economy faces stagnant growth, the government is proposing €54 billion in spending cuts to bring the deficit down to 5% by 2027. This structural tension has already sparked over 170 public protests across the country.
From a senior macroeconomic perspective, here is what this structural data means for the Eurozone ecosystem:
1️⃣ The Sovereign Debt Dilemma: When public debt crosses structural thresholds during periods of economic stagnation, a government's fiscal space shrinks. This forces a delicate balancing act between austerity and political stability.
2️⃣ The Monetary Friction: Raising interest rates is designed to cool demand-driven inflation. However, it cannot solve supply-side shocks, such as the energy costs driven by current geopolitical tensions.
3️⃣ Fiat System Dynamics: In traditional fiat architectures, when governments struggle to cut spending due to social pressure, long-term debt pressures historically lead to monetary debasement (inflation) rather than technical defaults.
This situation highlights the ongoing friction between central bank tightening, fiscal deficits, and real economy constraints.
[For educational purposes only — Not financial advice]
⚡ Zaps are welcome to support independent analysis!
#France #Macroeconomics #ECB #INSEE #Finance #Economie #debt #dette
If someone had invested $1,000 in Amazon at its IPO in 1997, they would be sitting on over $3.3 million today.
Their initial capital would have multiplied by a staggering 3,300 times! 📈
But to achieve such a result, that person would have had to hold onto their Amazon shares through incredible financial storms:
• 18 drops of 20% or more
• 4 crashes of over 50%
• A catastrophic -95% plunge after the Dot-Com bubble burst 📉
No investment can produce exceptional returns without major volatility. Long-term performance is simply the reward for managing your emotions.
The sooner you learn to endure this volatility, the better.
If you are not mentally prepared to see your portfolio drop by 30%, you are probably not ready to see it gain 300% either.
👉 Honestly, would you have held through a 95% crash? Let me know in the comments!
#Investing #Mindset #Amazon #LongTermInvesting #StockMarket #Volatility
Una persona che avesse investito 1.000$ su Amazon al momento della sua introduzione in borsa nel 1997, oggi si ritroverebbe con oltre 3,3 milioni di dollari.
Il suo capitale iniziale sarebbe stato moltiplicato per ben 3.300 volte! 📈
Ma per arrivare a un traguardo simile, questa persona avrebbe dovuto conservare le sue azioni Amazon superando tempeste finanziarie incredibili:
• 18 cali del 20% o più
• 4 crolli di oltre il 50%
• Un catastrofico -95% dopo lo scoppio della bolla delle Dot-Com 📉
Nessun investimento può produrre una performance eccezionale senza una volatilità importante. Il rendimento a lungo termine è il premio per chi sa gestire le proprie emozioni.
Prima si impara a sopportare questa volatilità, meglio è.
Se non siete mentalmente pronti a vedere il vostro portafoglio perdere il 30%, probabilmente non siete ancora pronti a vederlo guadagnare il 300%.
👉 E tu, saresti riuscito a non vendere durante un crollo del 95%? Scrivilo nei commenti!
#EducazioneFinanziaria #AmazonYour fear is 100% justified, and it's a question many are asking right now. However, this is exactly where the difference between "open-source code" and "how a company compiles it" becomes crucial.
Other reputable hardware wallets like BitBox02, Blockstream Jade, or Trezor are under continuous public scrutiny. Independent developers constantly review their open-source code to verify that the hardware randomness chip (TRNG) is working correctly alongside the software. The Coldcard disaster was a catastrophic firmware build error unique to Coinkite's development pipeline.
If you want absolute peace of mind without waiting for external audits, the ultimate solution is physical dice rolling 🎲.
Most advanced wallets allow you to supply the randomness yourself by rolling a die 100 times at home. This completely bypasses the manufacturer's chip. Even if a wallet has a hidden bug, it cannot manipulate math you generated with your own hands. Don't give up on hardware wallets; just take control of the entropy.
I just published a step-by-step breakdown of how this specific entropy bug worked and how you can use a simple $1 die to restore 100% confidence in your custody.
#bitcoin #security #coldcard #selfcustody #nostr #plebs #dicerolling 🟠₿ 🎲
Read it here:
https://yakihonne.com/article/s/scudofinanziario@nostrcheck.me/c5c65ee602123ff4
⚡
View quoted note →